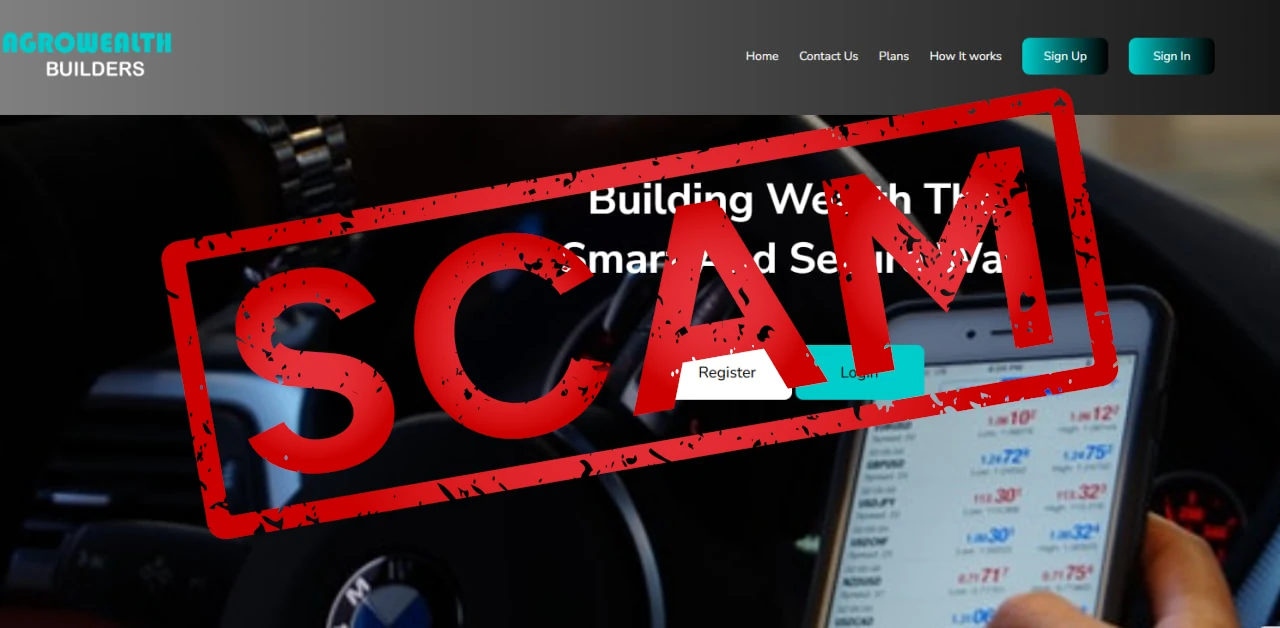
When a project promises not just profit but fixed daily returns, the first question is not whether the website looks polished. The first question is whether that model survives an ordinary regulatory and mathematical review. Agrowealthbuilder.com begins to fail precisely at that point. According to the screenshots you provided, the platform presents several investment plans, crypto-only payments, 24/7 withdrawals, a referral bonus, and a UK contact address. On the surface, the structure is simple and attractive: choose a plan, send funds, receive a predetermined daily return. But the higher and more stable the promised return, the more important the underlying proof becomes. A platform asking for money on that basis should be able to show a confirmed legal entity, a verifiable regulatory perimeter, and a credible explanation of where such returns are generated. Here, that foundation is missing.
The warning profile is not theoretical. The Bank of Russia has already listed Agrowealthbuilder, tied specifically to agrowealthbuilder.com, under “Signs of illegal professional securities market participant,” with the date of entry recorded as 03.03.2026 on the official page https://cbr.ru/eng/inside/warning-list/detail/?id=42962. For a platform that wants to be treated as a financial intermediary or investment service, that is not a secondary concern. It is the central fact of the case.
For UK and EU readers, the problem becomes sharper rather than softer. The screenshots show a platform using a UK-facing contact presentation while offering fixed daily profit packages and crypto-based entry. But under the FCA’s own consumer guidance, almost all financial firms in the UK must be authorised or registered, and dealing with an unauthorised firm means a consumer will not have Financial Ombudsman Service or FSCS protection if things go wrong. The FCA explains this directly on its warning-list page at https://www.fca.org.uk/consumers/warning-list-unauthorised-firms. That means the gap here is not cosmetic. It goes directly to investor protection.
| Parameter | Details |
|---|---|
| Project name | Agrowealthbuilder |
| Website | agrowealthbuilder.com |
| Domain registration date | 2026-02-15 |
| Registrar | Unstoppable Domains Inc. |
| Claimed jurisdiction | United Kingdom, based on the contact section shown in the provided screenshot |
| Claimed legal entity | not disclosed |
| Minimum deposit | USD 200 |
| Maximum leverage if applicable | not applicable / not disclosed |
| Claimed regulation | not disclosed |
| FCA verification result | no verifiable authorization confirmed |
| EU verification result | no verifiable EU authorization confirmed |
| Warning list status | listed by the Bank of Russia on 03.03.2026 |
| Risk classification | very high |
The table already shows the structural problem. The website asks for trust at the level of an investment platform, but the verifiable regulatory layer remains absent. According to your screenshots, the contact section shows 46 George Street, Broxwood, United Kingdom, plus [email protected] and [email protected]. The plan section shows daily return packages of 2%, 4%, 12% and 22%, crypto-only payments, 24/7 withdrawals, and a 10% referral reward. That combination is not neutral. It is a classic high-risk configuration that demands harder due diligence, not softer assumptions.
Is agrowealthbuilder.com regulated in the UK
If a platform is presented in a UK-facing way and solicits investor funds, the core verification source is the FCA Register at https://register.fca.org.uk/. That is where an investor should be able to verify whether the business is authorised and whether the service offered falls inside the UK regulatory perimeter. The FCA also states on its warning-list guidance that almost all financial firms in the UK must be authorised or registered by it, and if a consumer deals with an unauthorised firm, they will not be covered by the Financial Ombudsman Service or the Financial Services Compensation Scheme. That is a practical investor-protection point, not a technicality.
The review of official regulatory registers does not confirm the existence of any license. That conclusion matters because domain-level verification is what separates a real regulatory identity from a marketing impression. It is not enough for a platform to use a UK address or the language of finance. If the reviewed website cannot be tied to a confirmed authorised firm, authorisation cannot be attributed to the website. In this case, the reviewed evidence does not establish a confirmed FCA-authorised entity linked specifically to agrowealthbuilder.com. At the same time, an official warning-list record tied to the same domain does exist. For a UK retail investor, that is a material compliance failure.
This also affects how the platform should be interpreted operationally. A genuinely authorised UK intermediary does not begin with fixed daily return promises and crypto funding while leaving the legal structure in the background. It begins with legal verifiability. A user should be able to identify the regulated firm, check the authorisation, and understand what protections exist before money is transferred. With agrowealthbuilder.com, that sequence appears reversed.
How agrowealthbuilder.com fits into the EU regulatory gap
The EU side of the analysis leads to the same concern from a different angle. An EU-facing investment platform should fit inside a MiFID-style regulatory logic, with a verifiable entity, a national supervisor, and a clear legal basis for offering investment services cross-border. One of the clearest examples of an official EU supervisory source is CySEC at https://www.cysec.gov.cy/. Where that regulatory architecture cannot be verified, the platform should not be treated as benefiting from the ordinary assumptions investors associate with supervised firms in the EU.
For agrowealthbuilder.com, the problem is direct rather than abstract. The platform presents itself through fixed-return investment plans and asks for funds in crypto, but the reviewed evidence does not establish a confirmed EU-regulated entity tied to the domain. That means the ordinary protections that matter for EU retail clients remain unverified: ongoing regulatory supervision, a clear legal entity, client-money safeguards, and any meaningful compensation logic. A site can look financially themed without being institutionally real. That is exactly why direct regulatory confirmation matters.
The lack of a verified EU regulatory home also deepens the cross-border risk. If a project presents itself as accessible to international investors but does not provide a confirmed legal base inside a recognised supervisory structure, the investor is left with the website’s own narrative and very little else. That is a weak position in any financial dispute and a particularly weak position when returns are promised in fixed daily percentages.
What agrowealthbuilder.com screenshots reveal about the actual model
The screenshots you provided are unusually important here because they show the commercial core of the scheme in plain form. The platform is not presenting a classic brokerage model with disclosed execution, spread-based revenue, or a regulated intermediary framework. Instead, it presents four profit packages.
Bronze promises 2% daily, with investments from USD 200 to USD 1,000, a duration of 4 days, crypto payment, and a 10% referral bonus. Silver promises 4% daily, with investments from USD 1,000 to USD 5,000, a duration of 10 days, crypto payment, and the same referral bonus. Gold promises 12% daily, with investments from USD 5,000 to USD 20,000 over 10 days. The shareholder plan promises 22% daily, with investments starting from USD 20,000 and going up to USD 1,000,000, again with crypto funding, 24/7 withdrawals, and referral rewards. That is not the language of regulated portfolio management. It is the language of a fixed-return high-yield scheme.
The contact screenshot adds another layer. It shows a UK address and two domain-based email contacts, which helps the platform look structured and international. But contact formatting is not the same as legal transparency. A footer address and branded email accounts do not establish a regulated financial entity, a licence, or investor protection.
The agrowealthbuilder.com mathematical and structural risk model
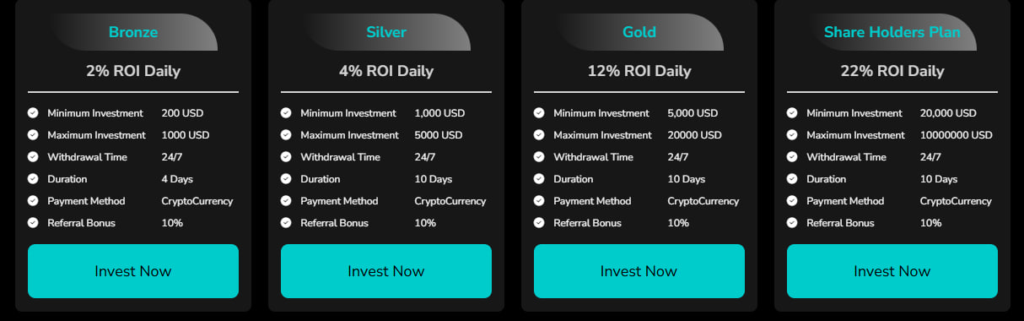
This is where the model becomes difficult to defend even before regulation is discussed. Take the Silver plan shown in the screenshot. A client deposits USD 1,000 and is promised 4% a day for 10 days. On simple arithmetic, that means the platform owes USD 400 in profit over 10 days, for a total payout of USD 1,400. That is a 40% return in 10 days.
Now look at Gold. A USD 5,000 deposit at 12% a day for 10 days implies USD 6,000 in profit over the period, meaning the platform owes USD 11,000 in total. The shareholder plan is even more extreme. A USD 20,000 deposit at 22% a day for 10 days implies USD 44,000 in profit, meaning total expected payout reaches USD 64,000. That is not simply “high yield.” It is mathematically aggressive to the point that the burden of proof shifts completely onto the operator. A platform making those promises needs to show an exceptional and verifiable source of return. Agrowealthbuilder.com does not.
A simple structural example shows why this matters. If 100 users deposit an average of USD 1,000, the platform receives USD 100,000. If only 25 of them later request payouts averaging USD 1,400 under the lower-tier plans, the site needs USD 35,000 of actual liquid outflow capacity. If some participants are on higher-yield plans, the required outflow climbs much faster. In a regulated and transparent model, that would be backed by a verified revenue source, capital structure, and operational controls. In a non-transparent model with no confirmed licence and no proven business engine, the most obvious explanation is deposit dependency: earlier obligations are being funded by later inflows.
That is why the referral bonus matters. A 10% recruitment reward is not a decorative feature in this structure. It is a built-in inflow engine. It encourages users to bring in new money, which can temporarily support the payout narrative. In professional terms, that points to a deposit-dependent structure with a clear liquidity-imbalance risk. The collapse trigger is also easy to understand. Once inflows slow and withdrawal pressure rises, the model stops looking like an “investment opportunity” and starts behaving like a cashflow problem.
The same point can be stated another way. A legitimate financial service normally explains how value is created. Agrowealthbuilder.com explains how money is collected and how returns are displayed, but it does not verifiably explain how those returns are economically produced. That gap is exactly where structurally unsustainable return logic begins.
The agrowealthbuilder.com address, jurisdiction and identity problem
The jurisdictional picture is weaker than the presentation suggests. The contact screenshot uses a UK address, but a claimed address is not the same as a verified regulated presence. Where a UK company is genuinely part of the legal and financial system, one of the relevant public starting points is Companies House, whose search guidance is available at https://www.gov.uk/guidance/search-the-companies-house-register. That matters because investors need more than a location label. They need a traceable legal entity that can be matched to the domain and to the claimed activity. Companies House itself also makes clear that the fact information is on the public record should not be taken to mean that it has been verified or validated in every respect, which makes domain-level and regulatory-level consistency even more important.
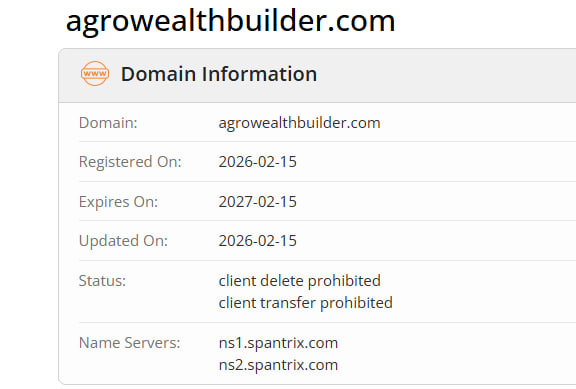
The domain-history profile shown in your screenshot is also telling. It shows registration on 2026-02-15, the same update date, expiry on 2027-02-15, registrar Unstoppable Domains Inc., and name servers ns1.spantrix.com and ns2.spantrix.com. That is a very new domain for a platform asking investors to believe in fixed daily profitability. Age alone does not prove misconduct. But in due diligence, domain age matters because a genuine financial platform with a real operational history usually leaves a denser trail. Here, the domain is new and the warning-list entry followed within weeks.
That short interval is one of the strongest facts in the case. A domain registered on 15 February 2026 and already linked to an official Bank of Russia warning by 3 March 2026 is not developing the profile of an established financial intermediary. It is developing the profile of a project that reached regulatory concern very quickly.
Absence of confirmed authorization means absence of regulatory investor protection. That point is the cleanest jurisdictional takeaway for UK and EU readers. Without a confirmed regulated entity tied to the website, investors cannot assume access to recognised complaint channels, compensation logic, or supervisory oversight. No Swiss claim appears in the provided material, so a FINMA analysis is not triggered here, but the relevant official source would be https://www.finma.ch/en/authorisation/ if such a claim were later made.
There is also a broader identity issue. A platform that genuinely wants to be treated as a financial intermediary should make verification easier as the review progresses. Agrowealthbuilder.com does the opposite. The closer the review gets to legal identity, regulatory confirmation, and supervisory attribution, the thinner the evidence becomes.
The agrowealthbuilder.com warning-list record and why it matters
The strongest public official signal attached to this project is the Bank of Russia warning-list record. The page at https://cbr.ru/eng/inside/warning-list/detail/?id=42962 identifies Agrowealthbuilder, links it directly to agrowealthbuilder.com, and records the sign detected by the regulator as “Signs of illegal professional securities market participant,” with the entry date 03.03.2026. This is exactly the kind of authority-level signal that should change the way the platform is assessed by retail investors. It is not an anonymous forum post. It is an official supervisory warning.
That matters for more than optics. Once a domain appears in an official warning list, the burden of trust changes. Investors are no longer looking at a neutral new website with incomplete documents. They are looking at a website that already carries an official external risk marker. In that setting, the new domain age, the missing licence, the opaque business model, and the fixed daily return promises all become heavier, because they are no longer isolated concerns. They begin to reinforce one another.
This is also where SEO and due diligence meet cleanly. Search users are not only asking whether the platform looks professional. They are also asking whether any official record already points to elevated risk. In the case of agrowealthbuilder.com, the answer is yes.
The agrowealthbuilder.com risk indicators table
| Risk indicator | Present |
|---|---|
| No FCA authorisation confirmed | Yes |
| No EU licence confirmed | Yes |
| Official warning-list presence | Yes |
| New domain | Yes |
| Fixed daily return promises | Yes |
| Crypto-only funding model | Yes |
| Referral-based recruitment element | Yes |
| No confirmed legal entity disclosed | Yes |
| No verifiable investor-protection framework | Yes |
| Deposit-dependent logic | Yes |
The table shows why this should not be reduced to a single concern. Agrowealthbuilder.com does not merely have an incomplete contact section or an undeveloped regulatory page. It combines multiple high-risk features that tend to appear together in pseudo-investment structures: very high fixed returns, crypto funding, referral incentives, a fresh domain, no confirmed regulatory base, and an official warning-list entry.
Agrowealthbuilder.com reviews and why they matter only after verification
Search users usually do not begin with regulation. They begin with phrases like “Agrowealthbuilder.com reviews,” “Is Agrowealthbuilder.com legit,” or “Agrowealthbuilder.com pays or not.” That is understandable, but the stronger order of analysis is the reverse. Start with official records, domain history, and legal transparency. Then assess how user concern fits into that framework.
In this case, the framework is already adverse before any anonymous commentary is considered. The domain is new. The platform promises fixed daily returns up to 22%. It uses crypto-only payments and referral mechanics. And the Bank of Russia has already attached an official warning signal to the domain. That means later user concern, if it appears, would not enter a neutral picture. It would enter a risk picture that is already heavily loaded.
That is also why the review intent around agrowealthbuilder.com is unusually easy to interpret. Users looking for “reviews” are usually asking a deeper question: is there any verified reason to trust the platform. Based on the reviewed evidence, there is no confirmed regulatory basis for that trust.
How agrowealthbuilder.com differs from a regulated intermediary
A regulated UK or EU intermediary works from legal transparency outward. It has an identifiable legal entity, a verifiable authorisation basis, a domain that can be checked against that authorisation, a recognised complaints route, and where relevant a compensation or supervisory framework. The investor is not expected to infer legitimacy from the plan page. The investor is expected to verify it through official sources such as https://register.fca.org.uk/ and https://www.cysec.gov.cy/. That is how institutional trust is supposed to work.
Agrowealthbuilder.com works in the opposite direction. First come the plans, the percentages, the “invest now” prompts, the 24/7 withdrawals, and the recruitment incentive. Only after that does the harder due diligence question appear: where is the verified licence, the confirmed legal entity, the domain-linked authorisation, and the recognised investor-protection framework. Those core supports do not appear in the reviewed evidence. What does appear is a new domain and an official warning-list entry. That is the opposite of institutional depth.
The contrast therefore is not stylistic. It is structural. One model begins with regulation and lets marketing follow. The other begins with marketing and leaves regulation unverified. For a retail investor, that distinction is decisive.
Is agrowealthbuilder.com legit or not
If the question is asked in strict evidential terms rather than emotional ones, the answer is clear enough. There is no confirmed basis to treat agrowealthbuilder.com as a verified regulated financial intermediary. The platform presents fixed daily returns, uses crypto funding, relies on referral incentives, does not provide confirmed regulatory transparency, and already appears in an official warning list. For a retail investor, that is not the profile of a platform that has earned legal trust.
That conclusion does not depend on dramatic wording. It depends on structure. A legitimate regulated platform should become easier to trust as verification proceeds. Agrowealthbuilder.com becomes harder to trust as verification proceeds. That is the difference that matters.
Is agrowealthbuilder.com safe for UK and EU retail investors
For UK and EU retail investors, the key question is practical rather than rhetorical. Can this platform be treated as a supervised financial intermediary that sits inside a verifiable investor-protection framework. Based on the reviewed evidence, it cannot. The combination of fixed daily return promises, crypto-only funding, referral incentives, no confirmed domain-linked authorisation, and official warning-list presence puts the platform far outside the comfort zone of ordinary regulated finance.
That does not mean every loss scenario has to be predicted in detail. It means the protective perimeter that should exist before funds are transferred has not been confirmed. In financial due diligence, that alone is enough to elevate the risk materially.
FAQ on agrowealthbuilder.com
Does agrowealthbuilder.com have FCA authorisation
No confirmed FCA authorisation tied specifically to agrowealthbuilder.com has been established in the reviewed evidence. The relevant official source is https://register.fca.org.uk/.
Is agrowealthbuilder.com regulated in the EU
No confirmed EU-regulated entity tied specifically to agrowealthbuilder.com has been established in the reviewed evidence. A relevant official supervisory source is https://www.cysec.gov.cy/.
Why is agrowealthbuilder.com considered high risk
Because the platform combines a very new domain, fixed daily return promises of 2%, 4%, 12% and 22%, crypto-only payments, a 10% referral incentive, no confirmed legal entity disclosure, and an official Bank of Russia warning-list entry at https://cbr.ru/eng/inside/warning-list/detail/?id=42962.
What does the agrowealthbuilder.com domain profile show
The screenshot evidence shows registration on 2026-02-15, expiry on 2027-02-15, registrar Unstoppable Domains Inc., and name servers ns1.spantrix.com and ns2.spantrix.com. That is a very short domain history for a platform presenting itself through fixed-return investment plans.
Is agrowealthbuilder.com safe for retail investors
Based on the reviewed evidence, the platform does not meet the standard of confirmed regulatory transparency that UK and EU retail investors should require before sending funds.
What should an investor do before trusting agrowealthbuilder.com
The first step is not to rely on the plan page or the contact footer. The first step is to verify authorisation, legal identity, and supervisory linkage through official sources. In this case, that verification does not produce a confirmed regulated status.
Final conclusion on agrowealthbuilder.com
Agrowealthbuilder.com cannot be treated as a verified regulated financial entity on the basis of the reviewed evidence. The website promises fixed daily returns of 2%, 4%, 12% and 22%, uses crypto-only payment logic, and includes a referral incentive, but it does not provide the level of confirmed regulatory transparency that UK and EU investors should require before sending funds. The strongest official public signal attached to the domain is not authorisation. It is the Bank of Russia warning-list entry at https://cbr.ru/eng/inside/warning-list/detail/?id=42962.
The risk here is not speculative. It is structural. The model combines unrealistic fixed-return logic, weak legal transparency, and official regulatory concern. Our experts recommend avoiding any financial interaction with this project.
If regulation cannot be verified, the risk is not speculative – it is structural.
Lost money with a broker? Find out how to get it back! Contact us at [email protected] , leave your name and phone number so we can get back to you. The Watchdog Online team stands guard over your safety — together we will make the Internet better!
Read also: https://watchdog-online.com/article/mentoris-mentoris-life-scam/ https://watchdog-online.com/reviews/ecolucre-com-review-scam/