Mentoris presents itself as a gamified ecosystem rather than a classic broker or investment firm. Its homepage frames the user journey as “Click,” “Earn coins,” “Make money,” and “Level up,” while the roadmap refers to TON wallet integration, advertiser agreements, a referral program, an internal token launch, scaling partner profits, and a future DEX listing. For a UK or EU retail audience, that is not a neutral entertainment profile. It is a monetized, token-linked model wrapped in game language.
That risk profile becomes much sharper once official warning data is added. The Bank of Russia has listed MENTORIS.LIFE among entities showing signs of illegal activity in the financial market and marks it specifically with “Signs of financial pyramid.” The same official entry identifies the project through the website mentoris.life and related Telegram entities, with the entry dated 03.03.2026. For search users asking “mentoris.life review” or “is mentoris.life legit,” that warning is not background noise. It is the central regulatory fact. https://cbr.ru/eng/inside/warning-list/detail/?id=42972
The legal transparency on the website does little to reduce that concern. The Terms of Service say the service is provided on an “as is” and “as available” basis, disclaim liability for damages, and direct users mainly to [email protected]. At the same time, the public-facing site does not identify a named licensed financial operator, a company number, a verifiable regulated entity, or a disclosed supervisory framework. In practical compliance terms, that leaves retail users with a financialized growth narrative but without normal accountability markers.
| Parameter | Details |
|---|---|
| Project name | Mentoris |
| Website | https://mentoris.life |
| Domain registration date | 2024-12-13 |
| Registrar | REG.RU LLC |
| Claimed jurisdiction | not disclosed |
| Claimed legal entity | not disclosed |
| Minimum deposit | not disclosed |
| Maximum leverage | not disclosed / not applicable on the public site |
| Claimed regulation | not disclosed |
| FCA verification result | not confirmed |
| EU verification result | not confirmed |
| Warning list status | Bank of Russia warning entry, signs of financial pyramid |
| Risk classification | High |
Why Mentoris raises immediate UK regulatory concerns
In the UK, investment services require authorization, and the official reference point is the FCA Register at https://register.fca.org.uk/. The review of official regulatory registers does not confirm the existence of any license. That matters because Mentoris does not disclose an FCA-authorized entity, does not present a domain-level link to an authorized firm, and does not provide the legal identity information that would allow a retail user to verify authorization properly. In FCA terms, branding and website presentation do not create regulated status.
The UK retail-protection framework is also very concrete. The FCA’s CFD restrictions for retail clients include leverage limits between 30:1 and 2:1, margin close-out protection, negative balance protection, and a ban on inducements designed to encourage trading. Alongside that, the FSCS explains that eligible investment claims may be protected up to set limits where a firm is within scope. Mentoris does not disclose any comparable investor-protection architecture, compensation arrangement, or regulated permissions. For users searching “can UK investors trust mentoris.life,” that absence is the answer in regulatory form. https://www.fca.org.uk/news/press-releases/fca-confirms-permanent-restrictions-sale-cfds-and-cfd-options-retail-consumers https://www.fscs.org.uk/what-we-cover/investments/
The EU position is no safer
For EU-facing activity, the benchmark is MiFID-style authorization, passporting logic, client-fund protections, and ongoing regulatory supervision. CySEC’s official site and its Cypriot investment firms section exist precisely so users can verify whether a firm is licensed and whether investor-protection structures are in place. The CySEC investor-compensation materials also make clear that the Investor Compensation Fund is tied to the regulated framework for eligible clients of Cyprus Investment Firms. Mentoris does not disclose a CySEC license, a Cyprus Investment Firm identity, or any verified EU authorization basis. The right reference points are https://www.cysec.gov.cy/ and https://www.cysec.gov.cy/en-GB/entities/investment-firms/cypriot/, and the disclosed public information does not bridge that gap.
The same logic applies to risk controls. ESMA’s product-intervention measures on CFDs imposed leverage limits from 30:1 down to 2:1 for retail clients because regulators regarded uncontrolled retail exposure as a serious investor-protection problem. Mentoris, by contrast, publicly combines money language, token plans, wallet integration, referral scaling, and future DEX listing without any disclosed recognized EU supervisory perimeter. That is not how regulated cross-border retail finance is normally presented. https://www.esma.europa.eu/press-news/esma-news/esma-renew-restrictions-cfds-further-three-months-1-may-2019
Mentoris.life review – how the model creates structural risk
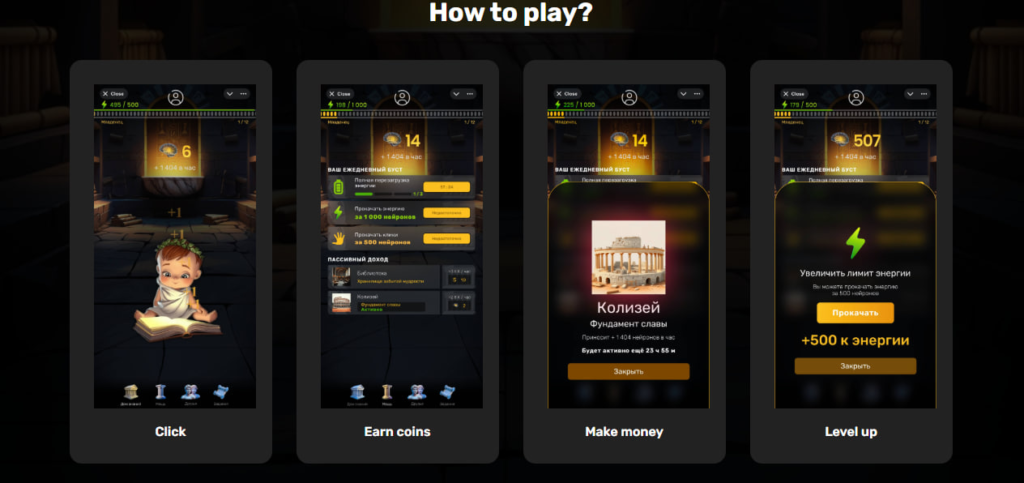
The key issue is not the playful interface. The key issue is economic substance. Mentoris describes a flow in which users click, earn coins, make money, and level up, while the roadmap adds wallet functionality, advertiser integration, token launch, referral expansion, and exchange listing. That means users are being conditioned to see internal activity as something that may later translate into realizable value. But the site does not disclose a transparent audited revenue engine capable of supporting those expectations at scale.
A simple calculation shows the pressure. Assume 10,000 active users come to expect only £20 each of realizable value from the internal model. That already implies £200,000 of value expectations. At 50,000 users, the same figure becomes £1,000,000. If the platform does not generate independently verifiable external cash flow on that scale, then the burden shifts toward continued user growth, referral expansion, token expectations, or hoped-for secondary-market liquidity. In professional compliance terms, that is what a deposit-dependent or inflow-dependent structure starts to look like, even if the platform avoids classic broker language. This is why “mentoris.life scam or legit” is not merely a branding question. It is a structural one.
The referral logic makes that problem worse. The roadmap includes both a referral program and a “Scaling Referral Program” aimed at growing partner profits. Once a model mixes internal tokenization, user-payment language, partner-profit scaling, and future DEX liquidity, the collapse trigger becomes easier to understand: inflows weaken, internal balances lose practical value, and the gap between interface value and real liquidity widens. Our analysts note that this is exactly why token-linked earning systems with weak disclosure tend to attract regulatory suspicion long before they can claim institutional credibility.
Is Mentoris.life legit or a scam?
From a strict legal-writing perspective, it is better to avoid unsupported criminal labels. But from a risk-analysis perspective, the profile is plainly adverse. There is an official central-bank warning for signs of a financial pyramid, no disclosed verified UK or EU authorization, no named regulated operator on the public pages, and a business narrative built around coins, money, token launch, referral growth, and exchange listing. A platform does not need to call itself a broker to create financial-risk exposure for retail users. https://cbr.ru/eng/inside/warning-list/detail/?id=42972
That is why the “legit or scam” search intent matters here. Users asking whether mentoris.life is safe are really asking whether the model offers verifiable investor protection, disclosed legal responsibility, and confirmed regulatory status. On the currently available public record, those confirmations are not there.
Jurisdiction and accountability gaps around Mentoris
Mentoris also performs poorly on basic accountability signals. The public-facing site does not disclose a corporate operator, registered office, phone support structure, or licensing perimeter. The Terms identify [email protected] as the contact point, but that is not equivalent to a verifiable regulated legal entity. For a model that publicly links participation to money and future token liquidity, the absence of a clearly disclosed operator is not a small omission. It is a core due-diligence failure.
That matters for both UK and EU audiences because investor protection depends on knowing who the regulated counterparty is, which authority supervises it, and where complaints can go. CySEC’s complaint guidance for Cyprus Investment Firms, for example, only makes sense inside a regulated firm framework. If no confirmed regulated entity is identified in the first place, those protections are out of reach. https://www.cysec.gov.cy/en-GB/investor-protection/how-to-complain/
Risk indicators around mentoris.life
| Risk Indicator | Present |
|---|---|
| No FCA authorization disclosed | Yes |
| No EU license disclosed | Yes |
| Official warning list presence | Yes |
| Signs of financial pyramid flagged by a central bank | Yes |
| No confirmed legal entity on the website | Yes |
| No compensation scheme disclosed | Yes |
| Internal token launch in roadmap | Yes |
| TON wallet integration in roadmap | Yes |
| Referral scaling / partner profit language | Yes |
| DEX listing in roadmap | Yes |
| Non-liability wording in legal pages | Yes |
| New-domain profile | Yes |
How a regulated UK/EU intermediary operates versus how Mentoris operates
A regulated UK or EU intermediary begins with identity, permissions, and investor protections. It tells users which legal entity operates the service, under which authorization, in which jurisdiction, and with what complaint and compensation framework. It does not ask users to infer legitimacy from momentum, branding, or future token plans. The relevant public verification points are https://register.fca.org.uk/, https://www.cysec.gov.cy/, and https://www.fscs.org.uk/what-we-cover/investments/
Mentoris begins from the opposite direction. It leads with gamification, coins, money language, token launch, referral growth, and future DEX listing. Its legal materials emphasize “as is” provision and limited liability, while the Bank of Russia has already attached a warning for signs of a financial pyramid. That is not how a regulated retail-facing financial model normally looks. It is how regulatory exposure accumulates while institutional trust remains unbuilt.
FAQ about mentoris.life
Is Mentoris.life regulated in the UK?
No confirmed FCA authorization is disclosed on the public-facing materials, and the FCA Register is the official place where such authorization would need to be verified. https://register.fca.org.uk/
Does Mentoris.life show an EU investment license?
The public website does not disclose a confirmed EU investment license or a verified regulated EU investment firm identity.
Is Mentoris.life on any warning list?
Yes. The Bank of Russia lists MENTORIS.LIFE with signs of a financial pyramid. https://cbr.ru/eng/inside/warning-list/detail/?id=42972
Why do users search for “mentoris.life review” and “mentoris.life scam”?
Because the project combines earning language, tokenization, referral scaling, and future DEX listing without confirmed regulatory transparency, which naturally raises due-diligence questions.
Mentoris.life – final compliance conclusion
Mentoris cannot be treated as a verified regulated financial entity for UK or EU investors. The publicly available record does not show a confirmed FCA authorization, does not show a confirmed EU investment license, does not identify a clearly verifiable regulated operator, and does not present the investor-protection framework expected in regulated markets. At the same time, the project has an official warning-list presence for signs of a financial pyramid and promotes a model built around coins, money, tokenization, referral scaling, and future exchange liquidity. https://cbr.ru/eng/inside/warning-list/detail/?id=42972
For retail investors, the risk is high and structural rather than cosmetic. Our experts recommend avoiding any financial interaction with this project.
If regulation cannot be verified, the risk is not speculative – it is structural.
Lost money with a broker? Find out how to get it back! Contact us at [email protected] , leave your name and phone number so we can get back to you. The Watchdog Online team stands guard over your safety — together we will make the Internet better!
Read also: https://watchdog-online.com/article/fincrest-fincrest-ltd-scam/