Introduction
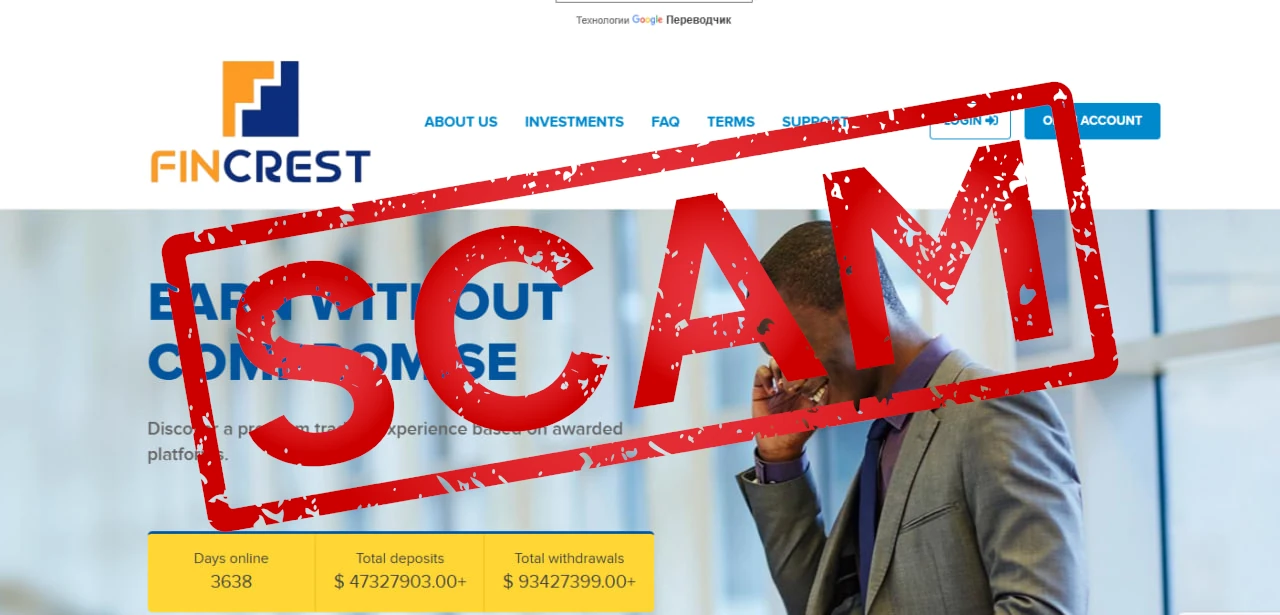
Fincrest (fincrest.ltd) presents itself as a UK-registered investment company operating under the name Fincrest Limited. The website displays a Companies House incorporation certificate dated 2020, references a London business address, and promotes fixed daily investment returns ranging from 3% to 7% depending on the selected plan. The presentation suggests corporate legitimacy through formal registration and structured investment tiers.
However, corporate incorporation is not equivalent to financial authorization. In regulated financial markets, legitimacy is defined by supervisory approval, prudential oversight, and enforceable compliance obligations. When a company advertises fixed daily returns while lacking confirmed regulatory authorization, the risk profile shifts from investment performance to structural sustainability.
On 26 February 2026, the Bank of Russia added fincrest.ltd to its official warning list, identifying the project as displaying signs of a financial pyramid:
https://cbr.ru/inside/warning-list/detail/?id=42877
Regulatory warning classification materially changes the compliance assessment. Our analysts note that fixed-return structures of this magnitude rarely operate within regulated financial frameworks because prudential supervision does not permit guaranteed exponential yield models.
General Information Table
| Parameter | Details |
|---|---|
| Project name | Fincrest |
| Website | https://fincrest.ltd |
| Domain registration date | 11 January 2026 |
| Registrar | HOSTINGER operations, UAB |
| Claimed jurisdiction | United Kingdom |
| Minimum deposit | From USD 100 |
| Maximum leverage | Not applicable (fixed-return model) |
| Claimed regulation | UK registered company (Companies House) |
| FCA verification result | No confirmed authorization via https://register.fca.org.uk/ |
| EU verification result | No confirmed listing via https://www.cysec.gov.cy/ |
| Warning list status | Listed by Bank of Russia as showing signs of financial pyramid |
| Risk classification | Critical |
UK Regulatory Compliance – FCA Authorization Requirement
Any firm offering investment services to UK retail investors must be authorized by the Financial Conduct Authority. The FCA register is the sole official public verification source:
https://register.fca.org.uk/
The review of official regulatory registers does not confirm the existence of any license.
Incorporation at Companies House merely confirms corporate existence. It does not authorize a firm to:
- Accept or manage retail investment funds
- Offer collective investment schemes
- Provide portfolio management
- Advertise fixed or guaranteed daily returns
An FCA-authorized firm must maintain:
- Prudential capital buffers under the Investment Firms Prudential Regime
- Segregation of client funds under CASS rules
- Regulatory reporting obligations
- Disclosure of risk warnings
- Participation in the Financial Services Compensation Scheme
Additionally, the FCA possesses enforcement powers including supervisory inspections, capital adequacy interventions, public warnings, and financial penalties. A platform operating outside this supervisory perimeter cannot provide enforceable regulatory recourse to investors.
Authorization is entity-specific and activity-specific. A corporate registration number does not create regulatory standing.
EU Regulatory Framework – MiFID II and Cross-Border Exposure
Within the European Union, investment firms must be authorized under MiFID II by a national competent authority. CySEC serves as one example:
https://www.cysec.gov.cy/
Licensed firms must maintain:
- Defined initial capital thresholds
- Ongoing own-funds compliance
- Governance and risk controls
- Client asset segregation
- Participation in Investor Compensation Fund mechanisms
- Supervisory reporting and audit trails
Passporting rights across EU member states require formal notification procedures between regulators. If a firm provides services across borders without documented passporting recognition, it operates outside the regulatory perimeter.
Fincrest does not appear in publicly verifiable EU regulatory databases. Therefore, EU retail investors cannot assume regulatory protection, compensation coverage, or supervisory dispute resolution access.
Mathematical and Structural Risk Analysis
Fincrest advertises fixed daily returns of up to 7%. Structural sustainability can be tested through compounding and liquidity stress modelling.
Scenario 1 – Compounding Redistribution Model
At 7% daily for 14 days:
1.07^14 ≈ 2.50
This implies a 150% return within two weeks.
If $1,000 is invested:
Day 14: $2,500
Day 28 (reinvested): $6,250
Day 42: over $15,000
Annualized compounding at 7% daily produces exponential growth inconsistent with regulated financial markets.
Such a structure implies redistribution rather than market-based yield generation.
Scenario 2 – Liquidity Coverage Stress
Assume:
300 investors deposit $2,000 each
Total capital pool = $600,000
At 7% daily:
Daily payout obligation = $42,000
Over 14 days:
$588,000 required payouts
This approaches total deposit volume.
Now assume 120 investors request withdrawal simultaneously:
120 × $2,000 = $240,000
If available liquidity equals $100,000:
Liquidity deficit = $140,000
Coverage ratio = 0.41
A coverage ratio significantly below 1.0 indicates deposit-dependent structural instability.
Our analysts note that such yield structures rely on continuous deposit inflow. When inflow slows, redistribution fails, triggering payout suspension conditions.
In regulated firms, capital buffers and segregated accounts prevent systemic liquidity failure. In unregulated fixed-return models, liquidity transparency cannot be independently verified.
Domain and Jurisdiction Analysis
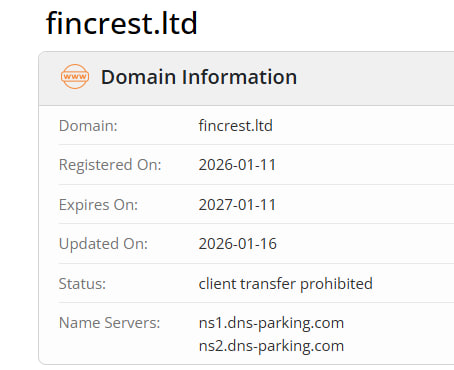
WHOIS records confirm:
- Domain created: 11 January 2026
- One-year registration cycle
- Registrar: Hostinger
- Standard shared DNS infrastructure
The company claims incorporation in 2020.
A six-year gap between incorporation and domain creation creates structural inconsistency. Established financial institutions typically maintain domain infrastructure aligned with corporate inception.
Short-term domain registration cycles are not characteristic of long-standing institutional investment firms.
The absence of historical digital continuity increases structural risk exposure.
Risk Indicators Table
| Risk Indicator | Present |
|---|---|
| FCA authorization absent | Yes |
| EU authorization absent | Yes |
| Official regulatory warning issued | Yes |
| Fixed daily return structure | Yes |
| New domain registration | Yes |
| One-year registration cycle | Yes |
| High referral incentive model | Yes |
| No capital adequacy disclosure | Yes |
Institutional Contrast
A regulated UK investment firm operates within enforceable supervisory architecture:
- Listed in FCA register
- Maintains prudential capital buffers
- Segregates client funds
- Participates in FSCS compensation framework
- Files audited regulatory reports
- Subject to supervisory inspections
- Provides structured complaint escalation channels
By contrast, Fincrest (fincrest.ltd):
- Does not demonstrate FCA authorization
- Does not appear in EU regulatory databases
- Has been flagged by a national regulator
- Operates under a recently created domain
- Offers fixed daily yield inconsistent with prudential supervision
- Provides no verifiable capital or liquidity transparency
The structural difference lies in enforceability. Regulation imposes accountability, capital adequacy, and oversight. Absent authorization, risk exposure transfers entirely to the investor.
Final Conclusion
Fincrest (fincrest.ltd) cannot be considered a regulated UK or EU investment provider based on publicly verifiable regulatory data. The absence of FCA authorization, the official regulatory warning issued by the Bank of Russia, the recent domain creation, and the fixed daily return structure collectively indicate a deposit-dependent high-risk model operating outside recognized supervisory frameworks.
Our experts recommend avoiding any financial interaction with this project.
Final Takeaway
If fixed daily returns exist without regulatory authorization, the risk is structural rather than market-based.
Lost money with a broker? Find out how to get it back! Contact us at [email protected] , leave your name and phone number so we can get back to you. The Watchdog Online team stands guard over your safety — together we will make the Internet better!
Read also: https://watchdog-online.com/article/is-axora-capital-cue-scam/