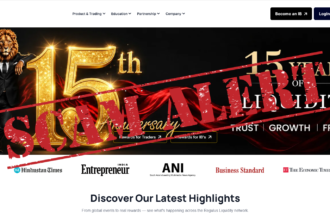
Investment platforms no longer sell people simple “trading.”
Today they sell atmosphere.
Dark terminal-style interfaces.
Canary Wharf addresses.
California offices.
Words like “institutional liquidity,” “professional execution,” “advanced analytics,” and “copy trading.”
And always the same promise:
even inexperienced users can supposedly “trade like professionals.”
AdvantCrest follows this model almost perfectly.
At first glance, the platform attempts to resemble a sophisticated international brokerage infrastructure designed for serious investors. Visitors are shown:
- hundreds of CFD instruments;
- leverage up to 1000:1;
- professional account structures;
- “global offices”;
- and claims of international regulation.
But the deeper the investigation goes, the more unstable this structure begins to look.
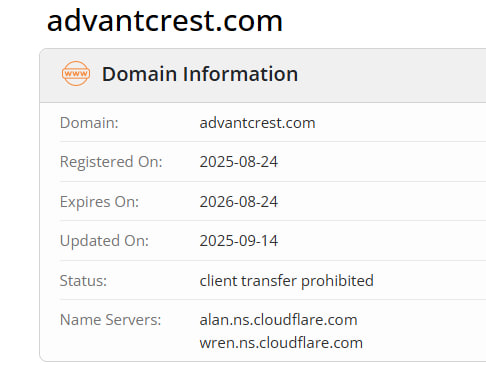
The domain advantcrest.com was registered only on:
August 24, 2025.
Yet only months later, the platform was already presenting itself as a global financial company with international trading infrastructure and professional investment services.
Then additional inconsistencies appear.
The website references SEC regulation even though the operational structure resembles a retail Forex / CFD broker model where NFA and CFTC oversight would normally be expected in the United States. The project uses a Canary Wharf address in London – one of the world’s best-known financial districts – yet no transparent FCA authorization can be verified. And in spring 2026, the platform received an official warning from the Spanish financial regulator CNMV.
At that point, AdvantCrest stops looking like a “young international broker” and starts looking like something very different:
a high-risk investment platform using institutional-style marketing to manufacture artificial credibility.
In this investigation we will examine:
- whether AdvantCrest holds verifiable licenses;
- why the CNMV warning is critically important;
- how the “registration does not equal regulation” model works;
- why leverage up to 1000:1 creates major investor risks;
- and why the combination of copy trading, fresh domain infrastructure, and questionable regulatory claims creates an extremely dangerous environment for retail investors.
General information about AdvantCrest
| Parameter | Details |
|---|---|
| Brand | AdvantCrest |
| Domain | advantcrest.com |
| Platform type | Forex / CFD / copy trading platform |
| Domain registration date | August 24, 2025 |
| Claimed regulators | SEC / FSA |
| Verified FCA authorization | not confirmed |
| Listed UK address | One Canada Square, Canary Wharf, London |
| Listed US address | Menlo Park, California |
| Phone numbers | +1 929 933 5402 / +1 607 202 9084 |
| Infrastructure | Cloudflare |
| Risk level | extremely high |
AdvantCrest and the official CNMV warning
The single most serious issue connected to AdvantCrest is the official warning issued by the Spanish financial regulator CNMV.
Official website:
https://www.cnmv.es/
According to publicly available information, AdvantCrest was included in the regulator’s warning list as an entity:
not authorized to provide investment services.
Within the European financial industry, appearance on a regulator warning list is not merely a reputational issue – it is a direct signal of elevated investor risk.
A regulator-level warning typically indicates:
- lack of verified authorization;
- investor protection concerns;
- absence of transparent regulatory oversight;
- and potential operation outside regulated financial frameworks.
For retail investors, this is one of the strongest warning indicators possible.
AdvantCrest and questionable SEC regulation claims
The platform’s regulation narrative deserves particular attention.
AdvantCrest references:
- SEC;
- FSA;
- international regulation;
- and “regulated trading environments.”
However, major inconsistencies immediately appear.
In the United States, retail Forex and CFD activities are normally associated with:
- NFA;
- and CFTC oversight.
Not SEC regulation.
This is a critically important forensic point.
The inconsistency creates the impression that:
- regulatory language may have been assembled superficially;
- the legal structure lacks transparency;
- and the platform’s licensing claims may not match the actual regulatory architecture expected for retail trading operations.
Investors can independently verify financial entities through:
- FCA — https://register.fca.org.uk/
- NFA — https://www.nfa.futures.org/
- SEC — https://www.sec.gov/
- CNMV — https://www.cnmv.es/
At the time of investigation, no transparent FCA authorization connected to AdvantCrest could be verified.
Fresh domain infrastructure and operational inconsistencies
WHOIS analysis shows that:
advantcrest.com
was registered only on:
August 24, 2025.
This is highly significant.
At the same time, the platform attempts to present itself as:
- a global financial company;
- a professional CFD broker;
- an advanced investment ecosystem;
- and an international trading infrastructure.
For a supposedly international brokerage operation, such recent infrastructure raises major questions.
Especially when the platform already claims:
- global market access;
- institutional-style services;
- hundreds of trading instruments;
- and sophisticated investment infrastructure.
The problem is that most inexperienced users check the design of a platform before checking its license.
AdvantCrest and the Canary Wharf legitimacy effect
Particular attention should be paid to the listed address:
One Canada Square, Canary Wharf, London
Canary Wharf is one of the world’s most recognizable financial districts.
For inexperienced users, such an address may create the impression of:
- institutional credibility;
- international legitimacy;
- and regulated UK operations.
However, a London address alone:
- does not confirm FCA authorization;
- does not prove regulation;
- and does not guarantee investor protection.
These elements are frequently used to simulate legitimacy and create institutional-style trust perception.
AdvantCrest and template-based broker characteristics
The platform demonstrates numerous characteristics commonly associated with template-based offshore broker projects:
- generic brokerage interfaces;
- repetitive financial language;
- standard account structures;
- excessively broad asset offerings;
- Islamic account options;
- copy trading marketing;
- and aggressive leverage promotion.
The website simultaneously offers:
- Forex;
- crypto CFDs;
- ETFs;
- commodities;
- indices;
- and hundreds of CFD instruments.
This “everything broker” structure frequently appears among:
- high-risk offshore brokers;
- white-label broker ecosystems;
- and template-based CFD operations.
Leverage up to 1000:1 – why this is extremely dangerous
One of the most concerning aspects of AdvantCrest is the leverage level:
up to 1000:1
This represents an extremely high-risk trading environment.
For comparison:
European regulators under ESMA imposed leverage restrictions specifically because excessive leverage dramatically increases retail investor losses.
Leverage at 1000:1:
- magnifies losses;
- accelerates liquidation risk;
- makes total account depletion highly probable;
- and increases dependency on broker-side execution.
The combination becomes especially dangerous when paired with:
- copy trading;
- beginner-focused onboarding;
- aggressive marketing;
- and simplified “easy investing” narratives.
AdvantCrest and copy trading risks
The platform heavily promotes copy trading as a simplified investment solution.
Marketing materials focus on:
- “easy investing”;
- one-click trading;
- beginner-friendly trading environments;
- and copying experienced traders.
However, copy trading:
- does not guarantee profits;
- does not eliminate risk;
- does not protect investors from losses;
- and may increase dependency on platform-controlled systems.
Without transparent regulatory oversight, such models become substantially riskier.
AdvantCrest and withdrawal-related concerns
One of the most common problems associated with unauthorized CFD platforms involves withdrawals.
External discussions already contain references to:
- withdrawal complaints;
- support silence;
- verification delays;
- and transaction disputes.
Independent reviews and discussions:
- https://tradersunion.com/scam-or-safe/advantcrest-review/
- https://www.fastbull.com/brokersview/brokers/advantcrest
- https://www.facebook.com/groups/446114750358448/posts/1293329428970305/
- https://www.instagram.com/p/DX5YYIRinfe/
These warning signals become especially serious in environments lacking:
- transparent regulation;
- investor compensation structures;
- and verifiable legal accountability.
Legitimate regulated brokers do not require:
- additional transfers to release withdrawals;
- “unlock taxes”;
- verification activation payments;
- or separate AML fees.
Any such requests should be treated as major warning signs.
AdvantCrest and artificial trust engineering
AdvantCrest actively attempts to create the image of:
- an international broker;
- a regulated investment environment;
- and a professional institutional trading platform.
To achieve this, the project uses:
- Canary Wharf positioning;
- US office references;
- regulatory terminology;
- institutional-style branding;
- broad market access claims;
- and copy trading narratives.
However, visual presentation alone does not replace:
- regulation;
- transparent licensing;
- investor protection;
- or verifiable legal accountability.
AdvantCrest – legitimate broker or high-risk investment platform?
At the time of investigation, AdvantCrest demonstrates multiple serious risk indicators:
- official CNMV warning activity;
- absence of transparent FCA authorization;
- questionable SEC-related claims;
- extremely fresh domain infrastructure;
- institutional-style marketing;
- template-based broker characteristics;
- leverage up to 1000:1;
- and withdrawal-related complaints.
This does not constitute a legal determination.
However, from a financial-risk and investor-protection perspective, the platform raises substantial concerns.
Particularly for investors who:
- plan to deposit significant funds;
- expect regulated broker protections;
- or assume that professional website presentation automatically means legitimacy.
Key risk indicators associated with AdvantCrest
| Risk indicator | Why it matters |
|---|---|
| Official CNMV warning | Regulator-level investor risk signal |
| Fresh domain infrastructure | No verified long-term operational history |
| SEC inconsistency | Questionable regulatory claims |
| Leverage up to 1000:1 | Extremely dangerous retail trading environment |
| Copy trading marketing | Increased risk for inexperienced users |
| Canary Wharf positioning | Artificial institutional credibility |
| Template-based broker structure | Signs of white-label broker ecosystem |
| Withdrawal complaints | Early operational risk indicators |
| Lack of FCA/NFA transparency | No transparent regulatory oversight |
FAQ about AdvantCrest
Does AdvantCrest hold an FCA license?
At the time of investigation, no verified FCA authorization could be identified.
Why is the CNMV warning important?
Because it represents an official regulator-level warning regarding unauthorized investment activity.
Why is leverage 1000:1 dangerous?
Such leverage dramatically increases investor losses and liquidation risks.
Does the SEC regulate retail Forex brokers?
Retail Forex regulation in the US is typically associated with NFA and CFTC oversight.
Are there withdrawal complaints connected to AdvantCrest?
Yes. External discussions already reference withdrawal-related and support-related concerns.
Final verdict on AdvantCrest
AdvantCrest demonstrates how many modern high-risk broker projects now operate.
Simple “get rich quick” websites are no longer enough.
Today these platforms increasingly rely on:
- institutional-style branding;
- Canary Wharf positioning;
- copy trading narratives;
- aggressive leverage promotion;
- and complex regulatory terminology.
Visually, such projects may resemble legitimate international financial brands.
That is precisely why regulator warnings become so important.
In the case of AdvantCrest, too many concerning elements appear simultaneously:
- extremely fresh infrastructure;
- questionable SEC claims;
- lack of transparent FCA authorization;
- leverage up to 1000:1;
- template-based broker characteristics;
- withdrawal-related complaints;
- and an official warning from CNMV.
Each issue individually would already represent elevated risk.
Together, they create a highly concerning profile for retail investors.
In financial markets, trust is built through transparent regulation, verifiable licensing, and real regulatory oversight – not through institutional-style branding, impressive office addresses, or promises of professional trading infrastructure.
Lost money with a broker? Find out how to get it back! Contact us at [email protected], leave your name and phone number so we can get back to you. The Watchdog Online team stands guard over your safety — together we will make the Internet better!
Read also: https://watchdog-online.com/reviews/fmpreshinvestmentplatform-trade-ponzi-hyip-scam-review/