Introduction: Goviaetinc review and regulatory positioning for UK and EU investors
Goviaetinc presents itself as an international multi-asset trading platform offering forex, commodities, indices, stocks and cryptocurrencies. The website promotes tiered account structures starting from $150 and escalating to $25,000, with leverage advertised up to 1:100. It references certification-style validation pages and includes compliance language linked to a VASP framework in Argentina.
For UK and EU retail investors searching for a Goviaetinc review, Goviaetinc FCA status, or whether Goviaetinc is legitimate, the central issue is regulatory verification. The platform does not display a confirmed FCA reference number. No CySEC licence number is provided. No passporting rights under MiFID II are documented.
Instead of primary supervisory confirmation, the website relies on external certificate-style domains. Our analysts note that when leverage exceeds retail regulatory caps and supervision cannot be verified through official registers, structural investor risk increases.
Regulation in the UK and EU is not a marketing claim. It is an enforceable framework. If authorisation cannot be independently confirmed, investor protection cannot be assumed.
General Information: Goviaetinc Platform Overview
| Parameter | Details |
|---|---|
| Project name | Goviaetinc |
| Website | goviaetinc.com |
| Domain registration date | 2019-11-07 |
| Registrar | GoDaddy.com, LLC |
| Claimed jurisdiction | Argentina VASP narrative |
| Minimum deposit | $150 |
| Maximum leverage | Up to 1:100 |
| Claimed regulation | External certificate-style validation pages |
| FCA verification result | No confirmed FCA entry |
| EU verification result | No confirmed CySEC or EU licence entry |
| Warning list status | Not confirmed in official FCA/CySEC registers |
| Risk classification | High risk – unverified regulatory status |
Goviaetinc FCA Status Explained
Investment services offered to UK retail clients require authorisation from the Financial Conduct Authority.
Official register:
https://register.fca.org.uk/
The review of official regulatory registers does not confirm the existence of any license.
A legitimate FCA-authorised broker provides:
- Legal entity name
- FCA reference number
- Defined permission scope
- Supervisory status
- Client money handling disclosure
FCA retail protection framework includes:
- Leverage caps generally limited to 1:30
- Negative balance protection
- Margin close-out rules
- Client fund segregation under CASS rules
- Access to the Financial Ombudsman Service
- Potential eligibility for FSCS
Marketing leverage of 1:100 does not align with FCA retail product intervention standards.
Without verified FCA authorisation, these safeguards are not enforceable.
EU Regulatory Framework: MiFID II and CySEC Oversight
Within the European Union, investment firms operate under MiFID II governance rules.
CySEC register:
https://www.cysec.gov.cy/
Regulated EU firms must demonstrate:
- Licence number
- Supervisory authority
- Fund segregation
- Investor Compensation Fund participation
- Passporting rights
Goviaetinc does not display a confirmed EU licence number or identify a supervised legal entity.
Absence of confirmed authorisation equals absence of enforceable EU investor protection.
Mathematical and Structural Risk Analysis
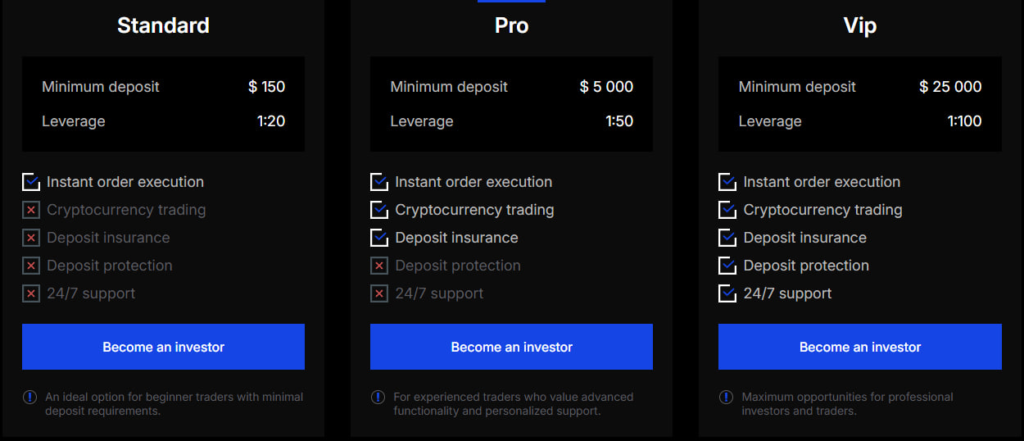
Leverage amplifies exposure.
Example 1:
Deposit $150
Leverage 1:20
Exposure $3,000
A 5% adverse move eliminates capital.
Example 2:
Deposit $25,000
Leverage 1:100
Exposure $2,500,000
A 1% adverse move equals $25,000 loss.
Retail leverage caps exist to reduce rapid capital erosion.
Structural risk intensifies when:
- Deposit tiers encourage escalation
- Withdrawal conditions lack clarity
- Legal supervision cannot be verified
- Compensation participation is not confirmed
Our analysts note that deposit-dependent models face liquidity imbalance when withdrawal volume exceeds inflow. Collapse triggers occur when operating liquidity cannot meet redemption demand.
Pattern Analysis: Goviaetinc and Related Platforms
Goviaetinc shares structural similarities with platforms such as Sowilli, Ecolucre and Whisperingdawns.
| Feature | Goviaetinc | Sowilli | Ecolucre | Whisperingdawns |
|---|---|---|---|---|
| No FCA licence | Yes | Yes | Yes | Yes |
| No EU licence | Yes | Yes | Yes | Yes |
| High leverage marketing | Yes | Yes | Yes | Yes |
| External certification domains | Yes | Yes | Yes | Yes |
| Tiered deposit escalation | Yes | Yes | Yes | Yes |
Repetition across multiple domains suggests templated deployment rather than independently supervised brokerage structures.
Goviaetinc Complaints and Withdrawal Concerns
Search queries including “Goviaetinc withdrawal problems”, “Goviaetinc complaints” and “Goviaetinc fund recovery” indicate investor uncertainty.
In regulated UK environments, disputes may be escalated to:
- Financial Ombudsman Service
- Regulator-supervised complaint channels
- Compensation schemes under defined eligibility
Without confirmed FCA or EU authorisation:
- Complaint escalation lacks regulator oversight
- Compensation schemes are not guaranteed
- Dispute enforcement depends on private legal action
Chargeback through card issuers may be available within defined time limits. Bank transfer recovery depends on rapid reporting and jurisdictional cooperation. Cryptocurrency transfers are generally irreversible once confirmed.
From a compliance standpoint, absence of regulatory supervision significantly reduces structured recovery pathways.
Is Goviaetinc a scam or a regulated broker?
Search intent such as “Is Goviaetinc a scam?”, “Is Goviaetinc legit?” or “Goviaetinc regulation check” focuses on regulatory status.
Based on publicly available information:
- No verifiable FCA authorisation is presented
- No confirmed EU licence number is displayed
- No passporting rights under MiFID II are documented
This assessment does not rely on speculation. In regulatory terms, absence of confirmed authorisation equals absence of regulated status.
For UK investors, this means no verified FCA supervision and no confirmed compensation coverage.
For EU investors, this means no MiFID II oversight and no confirmed investor compensation participation.
Risk Indicators Identified
| Risk Indicator | Present |
|---|---|
| No FCA authorisation | Yes |
| No EU licence | Yes |
| Leverage exceeding retail caps | Yes |
| No confirmed compensation scheme | Yes |
| No verifiable legal entity | Yes |
| External certification domains | Yes |
| Clone network similarity | Yes |
| Deposit escalation structure | Yes |
Institutional Contrast: Regulated Broker vs Goviaetinc Model
Regulated UK/EU broker:
- Public licence verification
- Segregated client funds
- Retail leverage caps
- Negative balance protection
- Margin close-out protection
- Compensation scheme participation
- Continuous supervisory oversight
Goviaetinc model:
- No verified regulatory entry
- High leverage marketing
- Certificate-style validation pages
- No confirmed compensation coverage
- No evidence of regulator-backed supervision
The operational difference is structural.
Final Regulatory Assessment
Goviaetinc cannot be considered a regulated UK or EU investment service provider based on publicly verifiable information. It does not demonstrate compliance with FCA authorisation requirements or MiFID II standards.
The structure presents elevated risk to retail investors due to unverifiable supervision and high leverage exposure.
Our experts recommend avoiding any financial interaction with this project.
Final Takeaway
If regulation cannot be verified, the risk is not speculative – it is structural.
Lost money with a broker? Find out how to get it back! Contact us at [email protected] , leave your name and phone number so we can get back to you. The Watchdog Online team stands guard over your safety — together we will make the Internet better!
Read also: https://watchdog-online.com/article/sowilli-net-scam/
https://watchdog-online.com/reviews/ecolucre-com-review-scam/