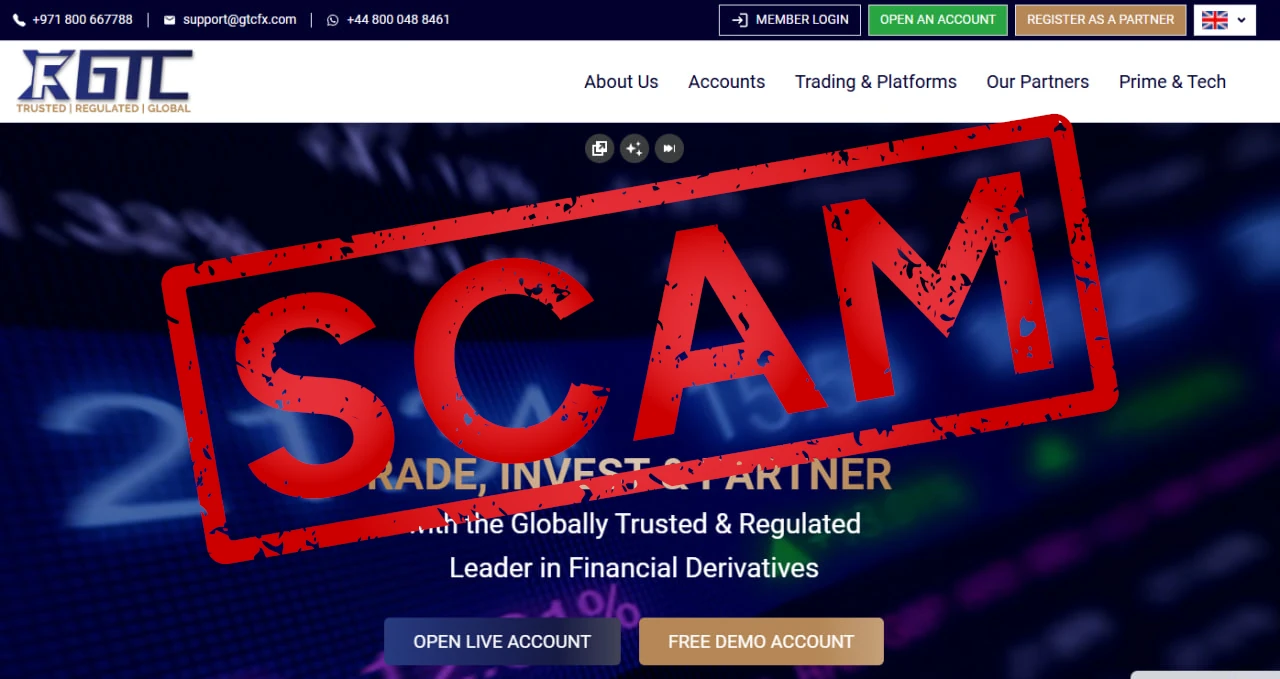
Key Information About GTC-RU.com
| Parameter | Details |
|---|---|
| Website | gtc-ru.com |
| Domain registration date | 30 September 2025 |
| Registrar | GoDaddy.com, LLC |
| Claimed group | GTC Global |
| Listed entities | GTC Global SA (South Africa), GTC Global Trade Capital Co. Limited (Vanuatu) |
| Claimed licences | FSP No. 51545 (South Africa), No. 40354 (Vanuatu) |
| Maximum leverage | Up to 1:2000 |
| Confirmed UK/EU authorisation | Not identified |
| Regulatory status | Brand appears in official warning list |
| Risk level | Elevated |
GTC-RU.com – A Regional Portal Under a Globally Marketed Brand
The website of GTC-RU.com claims to be a region-based gateway to the international brokerage group. Global presence, access to liquidity, and competitive spreads are emphasized.
On the surface, the structure looks organised and legitimate.
But in financial markets, legitimacy is not based upon branding. It is based upon regulatory authorisation.
Our analysts use a simple rule:
If the broker is seen to be targeting investors in that particular jurisdiction, it needs to appear in the official register of that jurisdiction.
That is the baseline.
GTC-RU.com and the Official Regulatory Warning
The GTC (Global Trade Capital) brand appears in the official warning list issued by the Central Bank of the Russian Federation:
https://cbr.ru/inside/warning-list/detail/?id=28093
This is not commentary.
This is not speculation.
It is a regulatory classification indicating signs of unlicensed activity.
When a national regulator places a financial brand in a warning register, the regulatory risk becomes structural.
Importantly, when a brand appears in such a list, any affiliated or newly launched regional domain inherits that regulatory risk unless clear evidence of independent authorisation is demonstrated.
The launch of a new regional domain in 2025 does not automatically eliminate that context.
GTC-RU.com – Newly Registered in 2025
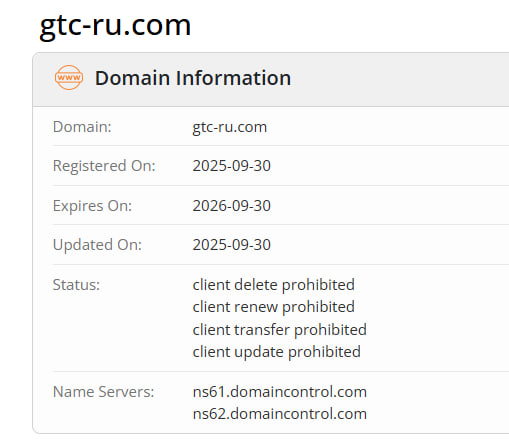
WHOIS data confirms:
- Domain registered 30 September 2025
- Registrar: GoDaddy
- Operational lifespan under one year
Despite this, the website positions itself under an established global identity.
In the financial sector, long-standing firms typically operate under consolidated domains and regulated entities.
Newly created regional portals often serve as:
- Market-specific acquisition channels
- Jurisdictional segmentation tools
- Traffic redirection points
Especially when regulatory scrutiny exists at the brand level.
Domain age alone is not proof of wrongdoing.
But in context, it becomes a relevant risk indicator.
Read also: https://watchdog-online.com/reviews/capital-flow-space-scam-review/
GTC-RU.com and Offshore Licensing – Regulatory Scope Matters
The website references:
- A South African FSP licence
- A Vanuatu financial services licence
These licences may exist within their respective jurisdictions.
However, regulatory scope is territorial.
A Vanuatu licence does not grant authorisation to operate in the UK or EU.
A South African FSP licence does not equate to FCA or CySEC authorisation.
For comparison:
FCA register (United Kingdom):
https://register.fca.org.uk/
CySEC register (European Union):
https://www.cysec.gov.cy/
If a broker actively targets UK or EU retail clients, MiFID-compliant authorisation is required.
No confirmed FCA authorisation is identified.
No confirmed EU investment firm licence is identified.
Corporate registration is not the same as financial regulation.
That distinction is critical.
GTC-RU.com and Leverage of 1:2000 – Outside Retail Protection Standards
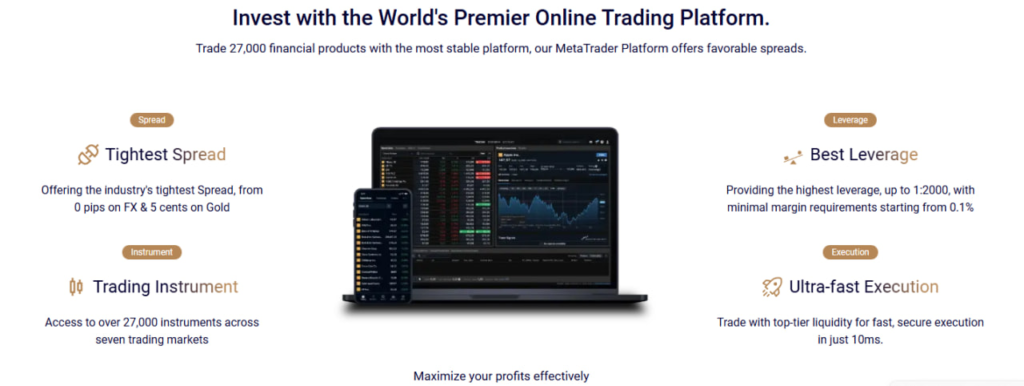
The platform advertises leverage of up to 1:2000.
For context:
- ESMA caps leverage at 1:30 for retail clients in the EU.
- The FCA applies the same 1:30 cap in the UK.
These restrictions exist to limit catastrophic losses for retail traders.
A leverage level of 1:2000 sits far outside these retail protection standards.
Such leverage is typically available only in offshore jurisdictions with lighter regulatory oversight.
High leverage attracts volume.
Regulated markets prioritise risk containment.
The difference reflects regulatory philosophy.
GTC-RU.com and Investor Protection Mechanisms
The website mentions:
- Negative balance protection
- Fast execution
- Advanced trading infrastructure
However, there is no confirmed evidence of:
- Participation in a statutory investor compensation scheme
- Membership in FSCS (UK)
- Inclusion in an EU Investor Compensation Fund
- Capital adequacy supervision under MiFID II
In regulated markets, investor protection mechanisms are enforceable by law.
Without confirmed supervision, protective claims remain internal company policies rather than statutory guarantees.
Our experts consistently emphasise that enforceable oversight is the defining characteristic of regulated financial services.
Jurisdictional Exposure and Cross-Border Risk
If clients deposit funds with an offshore or foreign entity:
- Dispute resolution may fall under foreign courts
- Domestic regulators may lack enforcement authority
- Recovery processes become significantly more complex
Jurisdiction determines accountability.
Branding does not.
When a broker operates outside the regulatory perimeter of the client’s country, the investor assumes cross-border legal risk.
External Discussions and Reported Concerns
Public discussions reference:
- Aggressive sales communication
- Confusion regarding regulatory status
- Withdrawal-related complaints
One isolated complaint does not define a company.
However, repeated patterns combined with official regulatory warnings elevate the overall risk assessment.
Regulatory context changes the weight of anecdotal reports.
What the Overall Structure Indicates
Based on publicly available information:
- The GTC brand appears in an official warning register
- GTC-RU.com is a newly registered regional domain
- Offshore licences are referenced as primary regulatory credentials
- Leverage of 1:2000 is offered
- No confirmed UK or EU authorisation is identified
Individually, each element may be explainable.
Collectively, they form a profile of elevated regulatory risk.
This analysis does not assert criminal conduct.
It highlights the absence of confirmed local regulatory supervision.
And in financial markets, absence of supervision is not a minor detail.
It is the core risk variable.
Final Assessment
At the time of review:
- The brand is listed in an official regulatory warning register
- No confirmed FCA authorisation is identified
- No confirmed EU MiFID authorisation is identified
- Offshore licensing is used as primary regulatory reference
- Extremely high leverage is promoted
If the broker is dealing with retail investors without registration in the appropriate directories, the risk remains completely with the client.
Supervision is not a marketing feature.
It is the foundation of financial accountability.
It is discretionary rather than enforceable in the absence of established supervision.
And in the realm of financial services, that difference marks out managed risk from structural vulnerability.
Lost money with a broker? Find out how to get it back! Contact us at [email protected] , leave your name and phone number so we can get back to you. The Watchdog Online team stands guard over your safety — together we will make the Internet better!
R